Market Overview: Defining the Engineered Stone Market landscape
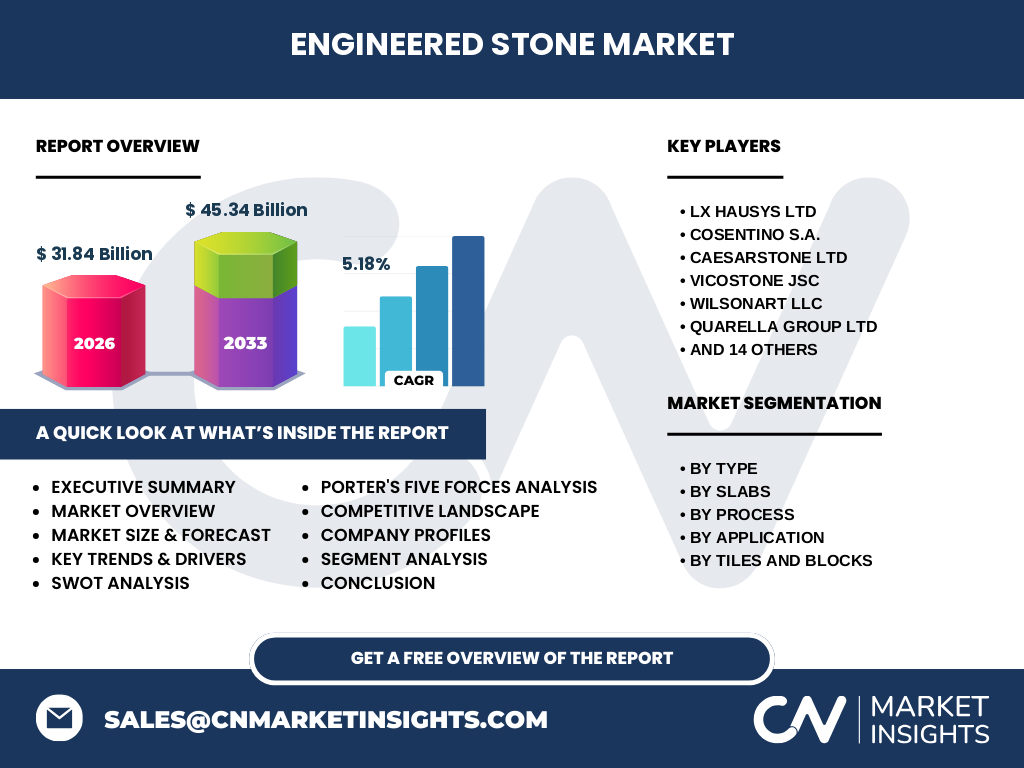
The Engineered Stone Market acts as a critical component of the global architectural surface industry. By synthesizing natural minerals and polymer resins, manufacturers create non-porous, durable slabs. Currently valued at 31.84 Billion in 2026, this sector signifies a major shift from traditional granite and marble toward standardized, high-performance materials essential for modern residential and commercial design.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by urbanization and high demand for low-maintenance kitchen surfaces. Conversely, the market faces constraints from stringent silica dust regulations enforced by health agencies like OSHA, which mandate sophisticated ventilation systems. Companies like LX Hausys Ltd and Cosentino S.A. mitigate these logistical hurdles by innovating in safer, high-durability manufacturing processes that circumvent traditional cutting-related health risks.
Emerging Trends in Engineered Stone Manufacturing
A pivot toward sustainable resin formulations and large-format thin slabs defines current industry trends. These innovations reduce weight and material waste, lowering transportation costs via major logistics hubs. The shift toward recycled glass and bio-based binders allows premium brands to command higher margins while addressing the environmental compliance requirements now standardized in European and North American building codes.
Impact of COVID-19 on the Engineered Stone Market
The pandemic catalyzed a housing renovation boom, shifting capital expenditure from travel to residential improvements. Despite supply chain disruptions at ports like Valencia or Shanghai, the market demonstrated resilience. Recovering swiftly, the sector adapted to contactless procurement, ensuring that Caesarstone Ltd and Vicostone JSC maintained continuity by pivoting distribution channels toward digital-first architectural specifications and localized warehousing.
Competitive Benchmarking and Market Concentration
The market features high strategic concentration among global players like Cosentino S.A., Caesarstone Ltd, and LX Hausys Ltd. These titans leverage vertical integration to control raw material sourcing. Smaller, regional innovators such as Viva Quartz Stone and Technistone A.S. compete by emphasizing localized design aesthetics and niche architectural applications, forcing major players to differentiate through patented technology and exclusive design partnerships.
Executive Summary of the Engineered Stone Market
Our analysis confirms a robust outlook for the Engineered Stone Market. With a projected market valuation of 45.34 Billion by 2033, we anticipate a steady CAGR of 5.18%. The synthesis of superior durability and design flexibility ensures the sector will remain a dominant force in high-end construction, provided manufacturers successfully navigate global environmental mandates and raw material supply volatility.
Market Forecast: 2027 to 2033
Between 2027 and 2033, we forecast the market to grow from its baseline toward a substantial 45.34 Billion valuation. This trajectory is supported by increased adoption of thin slabs in residential towers and the expansion of the commercial flooring segment. We expect the market to sustain a 5.18% CAGR as emerging economies industrialize and prioritize the aesthetic value of engineered stone.
Segmentation Analysis: Breaking Down the Value Drivers
Segments are divided by Type (Tiles and Blocks vs. Slabs) and Process (Cold vs. Hot Curing). Slabs dominate the market share, with thin slabs increasingly preferred for high-rise facades to reduce structural load. The hot curing process remains the industry standard for achieving optimal density, ensuring surfaces are resistant to bacterial growth and chemical stains.
Regional Market Distribution and Performance
North America and Europe currently hold the largest market share due to high residential spending, while the Asia-Pacific region displays the fastest growth rate. Rapid urbanization in China, driven by firms like Guangzhou Hercules Quartz Stone Co. Ltd, positions this region as a critical manufacturing hub. Performance variations are highly correlated with local construction permits and government-backed infrastructure development projects.
In-depth Regional Review
In North America, demand for countertops remains the primary revenue driver. Meanwhile, the European market—anchored by Quarella Group Ltd—is characterized by luxury aesthetics and strict environmental compliance. Asian markets exhibit a dual role, acting as both mass-producers and high-growth consumers. Regional logistics costs, specifically maritime freight rates, heavily influence the pricing structures and regional market competitiveness.
Company Profiles: Strategic Positioning of Industry Leaders
Leaders like Cosentino S.A. position themselves through brand prestige and extensive global distribution. Vicostone JSC leverages advanced manufacturing capacity to provide value-for-money solutions. Specialized firms such as Quartzforms and Diresco focus on unique surface textures and advanced mineral composites. These strategies enable firms to maintain pricing power despite the intense competition from smaller, low-cost regional manufacturers.
Porter's Five Forces Analysis
The Engineered Stone Market faces moderate threat from substitutes like natural stone or high-pressure laminates. Bargaining power of buyers is high due to fragmented distribution. However, barriers to entry—namely the high capital expenditure required for vacuum-vibration press lines and strict OSHA compliance—protect established players like Santa Margherita Spa and Wilsonart LLC from new, uncapitalized market entrants.
SWOT Analysis: Strategic Internal and External Audit
Strengths include product consistency and durability. Weaknesses involve high raw material reliance and health regulatory risks. Opportunities exist in the commercial facade sector and sustainable material innovation. Threats center on potential global trade tariffs and the tightening of labor regulations regarding silica exposure. Successfully navigating these risks requires firms to invest heavily in R&D for safer production environments.
Value Chain Analysis of Engineered Stone
The value chain begins with the extraction of quartz, silica, and color pigments. Manufacturing involves precise mixing and hot curing in industrial kilns. Distribution relies on a network of fabricators and retailers who bridge the gap to end-users. Value-add occurs primarily at the fabrication stage, where customized sizing and edge-finishing define the final market price for high-end residential and commercial projects.
Investment Insights and High-Potential Areas
Investors should monitor high-performance thin slabs, which offer significant margin potential in the commercial building segment. Partnerships with construction firms for large-scale urban development projects represent a stable ROI. Companies investing in silica-free formulations represent the most attractive long-term opportunities, as they are best positioned to navigate future regulatory shifts across global construction markets.
Conclusion and Key Takeaways
The Engineered Stone Market is poised for steady expansion toward 45.34 Billion by 2033. Success in this sector requires balancing aesthetic appeal with stringent safety compliance and manufacturing efficiency. Market participants must monitor the shift toward sustainable resin technologies and geographical diversification to maintain competitive relevance in a rapidly evolving, yet highly regulated, global architectural landscape.
Research Methodology
Our estimates are derived by triangulating trade registry data, primary stakeholder interviews, and macroeconomic building indices. We cross-reference manufacturer output figures with global import/export data from major ports. This bottom-up approach, combined with proprietary market sensitivity analysis, ensures our 5.18% CAGR forecast accurately reflects the underlying dynamics of the global engineered stone supply chain and consumption patterns.
Scope of the Report and Coverage Parameters
This report covers the global Engineered Stone Market, specifically segments categorized by type, process, and application. The research scope includes major regional contributors across North America, Europe, and Asia-Pacific. Limitations include localized price fluctuations due to currency volatility and the impact of regional construction policy changes. The analysis focuses strictly on commercial and residential surface applications.
Recent Developments and Market Announcements
Recent activity highlights a surge in strategic partnerships between material suppliers and global architecture firms. Significant product launches focusing on low-silica content characterize the latest output from LX Hausys Ltd and Caesarstone Ltd. These moves demonstrate a proactive response to health regulations, signaling that market innovation is currently focused on long-term safety compliance rather than just volume expansion.